Musharaka vs. Murabaha: How Two Halal Home Financing Structures Work

For many Muslim families, the question isn’t only whether they can afford a home, but how to finance one without riba. Two structures come up most often: Diminishing Musharaka and Murabaha. Both are built on real ownership and trade rather than lending money at interest, but they work in very different ways.
Why the structure matters
Islamic finance is built on principles that prohibit interest (riba), speculation (maisir) and excessive uncertainty (gharar). A conventional mortgage is a loan of money repaid with interest. A Halal structure replaces that loan with a partnership, a lease or a sale tied to an actual asset: the home itself.
Diminishing Musharaka: a partnership that shrinks
AAOIFI, the body that sets Shariah standards for Islamic financial institutions worldwide, describes Diminishing Musharaka as a partnership in which one partner promises to buy the other’s share gradually until ownership fully transfers. It combines three contracts: partnership (musharaka), lease (ijarah) and sale. In practice:
You find a home and negotiate the purchase.
Your down payment becomes your share of the partnership; the financier contributes the rest.
You live in the home and pay rent on the portion the financier still owns.
Alongside rent, you buy the financier’s share in portions over time.
As your share grows, the rent portion of your payment shrinks. Once you own every portion, the partnership ends and the home is yours alone.3 AAOIFI Shariah Standard No. 12 sets the conditions: each contract must be valid on its own, and the promises to buy and sell must be separate undertakings rather than conditions of the partnership.

Murabaha: a cost-plus sale
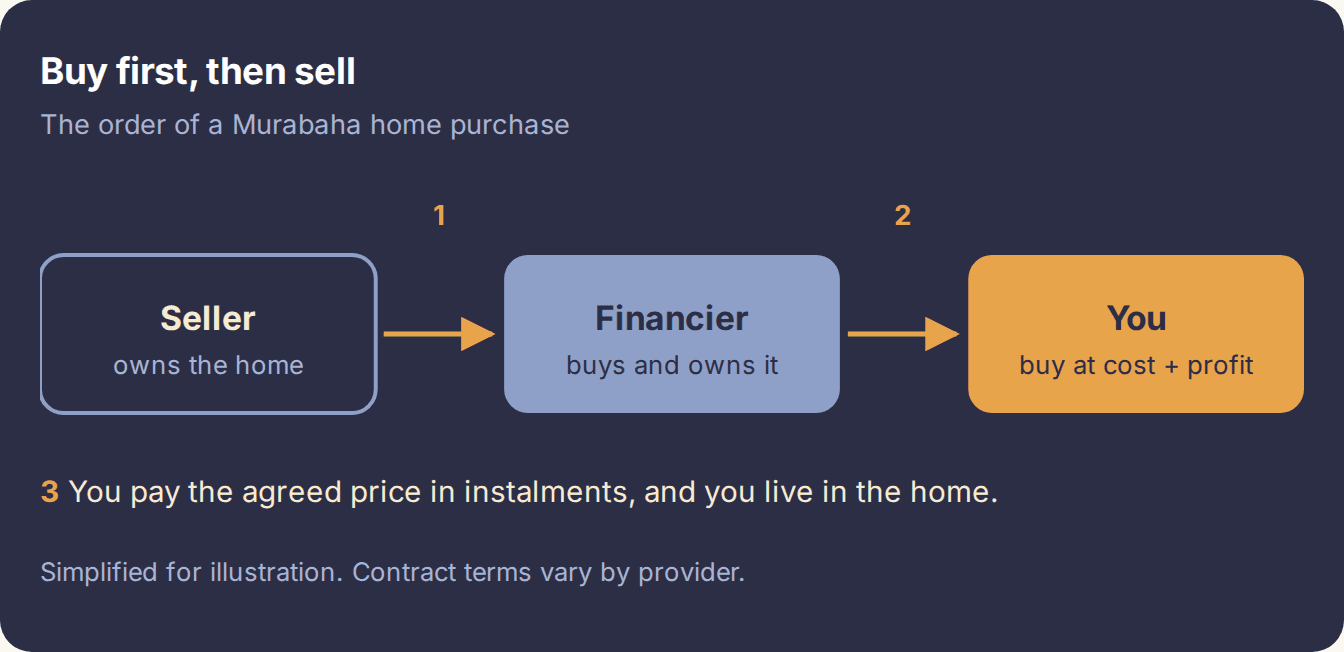
Murabaha is a sale in which the seller discloses what it paid and the profit it adds. In home financing:
You identify the home you want.
The financier buys it from the seller and takes ownership.
The financier sells it to you at cost plus a disclosed profit, payable in instalments.
Ownership is the condition everything rests on. Scholars ground it in the Prophet’s (ﷺ) instruction, “Do not sell what is not with you” (Abu Dawud 3503), so the financier must own the home before selling it to you. AAOIFI’s Murabaha standard (No. 8) also says the financier can’t hold back the property until the last instalment is paid; it can instead take the property as security.
The North American picture
Halal home financing isn’t new in North America, but it has been offered by a small number of providers rather than the big banks. In Budget 2024, the federal government said it would explore measures to expand access to alternative financing products such as halal mortgages, including possible changes to their tax treatment and a regulatory sandbox for providers.8 Like any financial product, halal mortgages remain subject to Canadian law.
Choosing a structure
Neither structure is automatically “more Halal” than the other. What matters is how the contracts are written and whether a qualified Shariah board has reviewed them. Before you sign with any provider, ask:
Which structure do you use, and why?
Who sits on your Shariah board, and can I see the certification?
What happens if I pay early, or miss a payment?
Sources
Torys LLP, Budget 2024: halal mortgages, April 19, 2024.
Blossom Finance, Diminishing Musharakah (Musharakah Mutanaqisah), citing AAOIFI.
Curtis, Mallet-Prevost, Colt & Mosle LLP, Islamic Banking: Home Purchase Financings Part II, Musharaka Mutanaqisa, August 31, 2012.
Abu Hamra, Zakariyah and Saleh, Diminishing Musharakah in Islamic Banks, At-Tajdid (IIUM).
General Iftaa’ Department of Jordan, Fatwa No. 816: Islamic Bank Must Own Commodity before Selling it to Client, 2010.
AAOIFI, Shari’ah Standard No. 8: Murabahah (scope summary).
General Iftaa’ Department of Jordan, Fatwa No. 2716, citing AAOIFI Shari’ah Standard No. 8.
Government of Canada, Budget 2024, as summarized by Mortgage Professional Canada.
This content is for informational purposes only and is not investment, financial, tax, legal or Shariah advice. Always consult a qualified scholar for matters of religious ruling.
For many Muslim families, the question isn’t only whether they can afford a home, but how to finance one without riba. Two structures come up most often: Diminishing Musharaka and Murabaha. Both are built on real ownership and trade rather than lending money at interest, but they work in very different ways.
Why the structure matters
Islamic finance is built on principles that prohibit interest (riba), speculation (maisir) and excessive uncertainty (gharar). A conventional mortgage is a loan of money repaid with interest. A Halal structure replaces that loan with a partnership, a lease or a sale tied to an actual asset: the home itself.
Diminishing Musharaka: a partnership that shrinks
AAOIFI, the body that sets Shariah standards for Islamic financial institutions worldwide, describes Diminishing Musharaka as a partnership in which one partner promises to buy the other’s share gradually until ownership fully transfers. It combines three contracts: partnership (musharaka), lease (ijarah) and sale. In practice:
You find a home and negotiate the purchase.
Your down payment becomes your share of the partnership; the financier contributes the rest.
You live in the home and pay rent on the portion the financier still owns.
Alongside rent, you buy the financier’s share in portions over time.
As your share grows, the rent portion of your payment shrinks. Once you own every portion, the partnership ends and the home is yours alone.3 AAOIFI Shariah Standard No. 12 sets the conditions: each contract must be valid on its own, and the promises to buy and sell must be separate undertakings rather than conditions of the partnership.
Murabaha: a cost-plus sale
Murabaha is a sale in which the seller discloses what it paid and the profit it adds. In home financing:
You identify the home you want.
The financier buys it from the seller and takes ownership.
The financier sells it to you at cost plus a disclosed profit, payable in instalments.
Ownership is the condition everything rests on. Scholars ground it in the Prophet’s (ﷺ) instruction, “Do not sell what is not with you” (Abu Dawud 3503), so the financier must own the home before selling it to you. AAOIFI’s Murabaha standard (No. 8) also says the financier can’t hold back the property until the last instalment is paid; it can instead take the property as security.
The North American picture
Halal home financing isn’t new in North America, but it has been offered by a small number of providers rather than the big banks. In Budget 2024, the federal government said it would explore measures to expand access to alternative financing products such as halal mortgages, including possible changes to their tax treatment and a regulatory sandbox for providers.8 Like any financial product, halal mortgages remain subject to Canadian law.
Choosing a structure
Neither structure is automatically “more Halal” than the other. What matters is how the contracts are written and whether a qualified Shariah board has reviewed them. Before you sign with any provider, ask:
Which structure do you use, and why?
Who sits on your Shariah board, and can I see the certification?
What happens if I pay early, or miss a payment?
Sources
Torys LLP, Budget 2024: halal mortgages, April 19, 2024.
Blossom Finance, Diminishing Musharakah (Musharakah Mutanaqisah), citing AAOIFI.
Curtis, Mallet-Prevost, Colt & Mosle LLP, Islamic Banking: Home Purchase Financings Part II, Musharaka Mutanaqisa, August 31, 2012.
Abu Hamra, Zakariyah and Saleh, Diminishing Musharakah in Islamic Banks, At-Tajdid (IIUM).
General Iftaa’ Department of Jordan, Fatwa No. 816: Islamic Bank Must Own Commodity before Selling it to Client, 2010.
AAOIFI, Shari’ah Standard No. 8: Murabahah (scope summary).
General Iftaa’ Department of Jordan, Fatwa No. 2716, citing AAOIFI Shari’ah Standard No. 8.
Government of Canada, Budget 2024, as summarized by Mortgage Professional Canada.
This content is for informational purposes only and is not investment, financial, tax, legal or Shariah advice. Always consult a qualified scholar for matters of religious ruling.